


Planning an HDB renovation loan starts with an itemised renovation scope, not the maximum amount a bank might lend. Separate essential works, optional improvements and purchases you can defer. Then check which costs a lender will accept and whether the repayments fit your household budget.
A renovation loan is separate from the housing loan used to buy your flat. It also does not replace HDB renovation permissions. This guide focuses on coordinating finance with an HDB renovation; use our Singapore renovation loan comparison checklist when reviewing borrowing terms.
Build a Finance-Ready Renovation Scope
Ask your designer for a quotation that identifies the property, contractor, work items, quantities, allowances and payment milestones. Separate fixed installations from loose furniture and appliances. Do not assume every item in a renovation package qualifies for the same financing product.
| Budget section | What to clarify |
|---|---|
| Essential renovation | Which works are required, their agreed specifications and the lender’s eligibility rules. |
| Optional upgrades | What can be reduced or postponed without compromising the essential scope. |
| Furniture and appliances | Separate purchase costs and whether the chosen product permits them. |
| Unconfirmed work | Site checks still needed and how additional costs would be authorised. |
Keep Loan Approval and Renovation Approval Separate
For your proposed works, ask the contractor to identify permit requirements and restrictions using HDB’s renovation information. A bank accepting a quotation does not mean the building works are permitted. Resolve uncertain alterations before treating them as a confirmed cost.
For a new flat, identify the supplied finishes and fittings you intend to retain. For a resale flat, have relevant existing conditions assessed before committing to a fixed replacement scope. Avoid treating an early estimate as a final construction quotation.
Ask the Lender for Its Current Document Checklist
Confirm the applicant and property eligibility criteria directly. Ask which identity, income, ownership and contractor documents are required for your circumstances, including joint applications where relevant. Requirements and assessment outcomes vary; an online illustration is not an approval.
Product limits are not universal borrowing entitlements. For example, DBS’s renovation loan page describes its own conditions and checks on the use of funds. Read the current offer and ask how it applies to your quotation rather than assuming another bank follows the same rules.
Match Disbursement to the Contractor’s Payment Schedule
- Who receives the funds, and when can payment actually be made?
- Which deposit or milestone costs must you cover yourself?
- What happens if the approved loan is smaller than expected?
- How are cancelled work, quotation changes and refunds handled?
- What evidence of completed works or expenditure must be retained?
Do not promise a payment date based only on an application submission. Agree a realistic sequence with both parties before work starts.
Review Affordability Before Signing
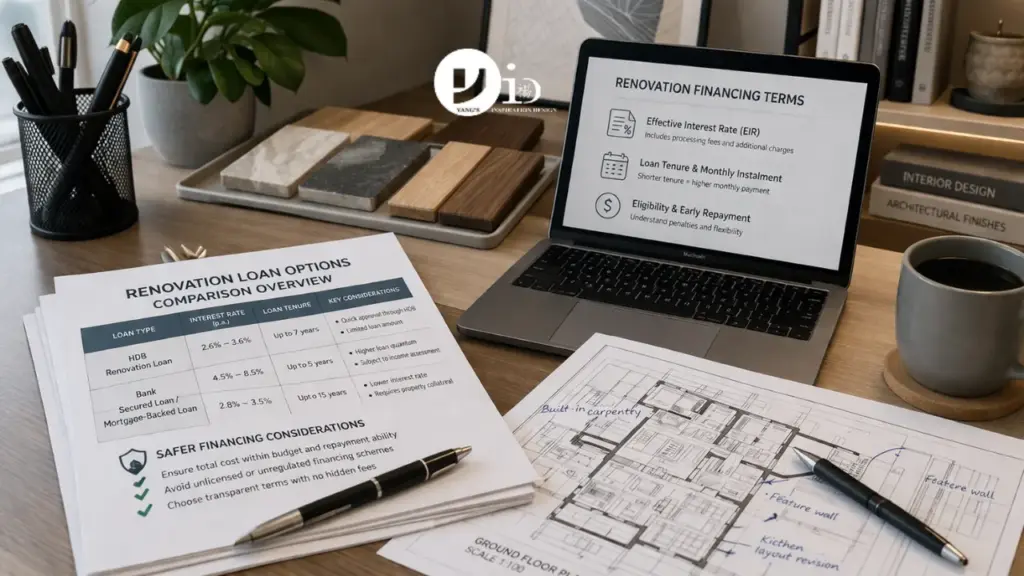
Compare the effective interest rate, instalments, total repayment and relevant fees in the actual offer. Allow for other household commitments and costs outside the loan. Reducing the scope or completing optional purchases later may be more suitable than increasing borrowing.
Can a renovation loan cover every item in my HDB package?
Not necessarily. Have the lender check the itemised quotation and identify exclusions before relying on the loan to fund it.
What should I bring to a renovation consultation?
Bring the floor plan, retained-item list, essential works and a budget boundary. Our HDB interior design team can discuss the renovation scope; the lender must confirm finance eligibility and terms.
General planning information, not personalised financial advice. Confirm current terms directly with the lender before committing.

March 27, 2026
Yang's Inspiration Insight